
Welcome to AstrologyOz
Apologies to all those who rely on this resource.. I have had major server issues which are now hopefully fully resolved.... after 4 months... I will be updating everything over the next week .... so thanks for your patience :)
|
|
|
World
News 2014
|
|
All your planetary data for 2014 is here now Planetary stations , Void of Course Moon , Moon phases and Planet Ingresses for 2014 plus Moon Planting Guide |

|
Jan - April 2014 Planting Guide
,
plus 2014 Moon phases,Planet Ingresses and retrogrades,
|
What Venus Retrograde in Capricorn Means for Finances in 2025The 2025 Venus retrograde is a time to review money, values and commitments, not a prediction of loss. Astrologically, Venus connects personal worth, spending, income and shared resources; when it turns retrograde, attention turns inward. Choices made for appearance, pressure or habit can look weak beside long-term goals. Venus stationed retrograde at 13° Capricorn on 1 March and turned direct near 24° Pisces on 4–5 May, depending on Australian time zone. It moved between Capricorn and Aquarius before continuing into Pisces. The opening emphasis concerns security and practical value; the closing phase turns towards what genuinely enriches life. For Australian readers, the useful questions are concrete: Which bills feel heavier than expected? Is an investment based on evidence or fear? Could better use of savings replace an impulse purchase? Use the cycle for organised judgement, not panic or speculation. Timing and the central financial themeCapricorn is an earth sign associated with structure, resourcefulness and the long game. With Venus at 13° Capricorn, the early retrograde favours checking whether income, spending and savings support the life being built. It highlights value for money, stability and commitments that outlast an emotional burst. Retrograde symbolism often brings overlooked details forward: an insurance excess, a poorly timed mortgage decision, an unused subscription or an undocumented business expense. Capricorn asks whether a financial choice has a sturdy foundation. Tazeen’s astrology perspectives can add context to recurring personal cycles. As Venus nears its direct station in Pisces, the review can move from strict control towards a values-led balance. This may separate necessary generosity from financial avoidance or reveal that a practical goal no longer satisfies. Astrology remains a reflective tool, not licensed financial advice. Money habits under reviewRetrograde Venus is often linked with second-guessing what is worth buying and why. A home project, holiday, wardrobe upgrade or gift may be reconsidered for usefulness and emotional truth. This can uncover costs missed when the purchase looked new or exciting. Income deserves equal scrutiny. A freelancer may revisit an underpriced quote, while an employee may compare salary with take-home pay after tax, superannuation and commuting. Existing debts become easier to manage when balances, interest rates and repayment dates sit in one place. Look for patterns rather than isolated worries. Repeated overspending, neglected paperwork or reluctance to negotiate a fee can reveal the habit that most needs attention. The goal is clarity, not pessimism. Comparing the retrograde phasesThe retrograde contains distinct movements, each supporting a different financial question. The comparison covers the opening Capricorn emphasis, the middle movement through Capricorn and Aquarius, and the closing approach to Pisces.
Exact station times and positions can be checked through Australian planetary data. This distinction prevents a common mistake: applying a Venus in Capricorn reading to the whole period without allowing for sign changes as Venus moves. The middle phase reveals gaps between a budget and personal values. A cheaper option can create waste, while a higher price may save time or last longer. The direct phase supports integration: turn insights into thresholds, deadlines and a plan that withstands market noise. Australian money pressures in focusAustralia’s household finances have local features worth including. The Reserve Bank cut its cash-rate target from 4.10 per cent to 3.60 per cent during March and April 2025. People with variable loans may see repayments move as the rate changes, so actual cash flow should be checked rather than assumed. City markets add another layer. Auction seasons and rental pressure in Sydney, Melbourne and Brisbane can make a property decision feel urgent, even when a new commitment exceeds a comfortable buffer. Compare purchase costs, vacancy or maintenance expenses and the effect on emergency savings before borrowing on market expectations. The Australian tax system and superannuation cycle are practical checkpoints. Reviewing an ATO tax return or deduction records can expose overpayments, while checking a superannuation balance may reveal a long-term gap. These are concrete financial habits, not astrological rules, and they deserve the same scrutiny as spending. Currency and consumer credit complete the picture. A shifting Australian dollar affects imported goods and international holdings, including some ASX portfolios. Weekly Woolworths, Coles or Aldi spending and buy now, pay later instalments can quietly become budget pressure. Federal reforms to place most buy now, pay later products under the National Consumer Credit Protection Act progressed through 2025, making these commitments important to a full debt review. A practical financial review checklistStart with a short cash-flow audit. Use a recent payslip, bank export or income record, then subtract regular commitments and essential living costs. Keep the list specific enough to reveal where pressure is occurring. Then test the decisions attached to that spending. Separate needs from wants and give uncertain expenses a deadline for review. Cash-flow audit
Decision audit
Turning the review into a clear money planThe strongest financial expression of this cycle is deliberate action: correct a mismatch between income and obligations, renegotiate one recurring cost, or redirect part of an impulse purchase into a buffer. Small changes can create more freedom than waiting for an imagined lucky break. Use the dates as organisational milestones. By the early-May direct station, the review should have become a written budget, a prioritised spending plan and at least one completed adjustment. Keep astrological interpretation separate from market timing, especially for property, investments or new debt. Begin the review today. Gather the records, identify the cost that needs attention and put a date beside every major financial decision before Venus turns direct. |
|
|
|
Benedict
XVI resigns 2013
|
|
|
|
Election
2013- take 2
|
|
|
|
Turkey
Unrest 2013
|
|
|
|
Election
2013
|
|
|
|
World
News 2013
|

|
|
|
Serialised
story of the greates ship of her time and
|

|
|
|
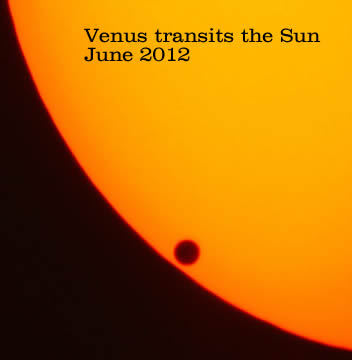
Venus
transits the Sun
|

|
For all your horoscopes, we recommend Ed Tamplin's excellent astrology site.

|
Astrology Oz is best viewed using firefox, screen resolution 1280x1024, macromedia flash enabled.
Firefox - the only browser that gives total control over web browsing, see what you want to see - download firefox

© AstrologyOz 2014
All articles and images on this site are subject to copyright and may not be copied, stored or modified in any way.
AstrologyOz - designed and maintained by Sherrynne Dalby